Tag: music

  • The future of subscriptions

    The future of subscriptions

    Last week Spotify filed for listing. The world’s largest music streaming business is looking to IPO which is likely not only to increase the profile of the business but also heighten scrutiny of its business model. Much has been written about the sustainability of Spotify and SVOD services in general. Spotify has both an ad-supported business model and a premium subscription service which makes it more akin to YouTube than Netflix, which it often gets compared to. With the increased scrutiny of streaming business models its worth considering what the future of media subscriptions might be – what’s currently happening and where it may end up.

    Subscriptions now

    Deloitte’s Telecommunication, Media and Technology Predictions for 2018 predicts that by end of 2018, 50% of adults in developed countries will have at least two online-only media subscriptions, and by the end of 2020 that average will have doubled to four. The heaviest users (1 in 5 adults in developed countries) will spend over $1200 annually on subscriptions for content including TV, movies, music, news and magazines. This is not new behavior – subscriptions in a more analogue world (newspapers, magazines, etc.) declined in the online revolution of the 1990s as people accessed more content for free. However, digital has seen a renewed rise in subscriptions due to a few key drivers:

    • Consumers have realised that not all content is equal and premium content comes at a price. This is particularly true in the age of fake news
    • Technology has advanced access to digital services, making it easier through speed, quality of experience and depth of libraries/back-cataloagues
    • Increased penetration of power mobile technology and better networks has made on-the-go consumption possible
    • Subscriptions often enable the avoidance of advertising (to various degrees)
    • In a world where digital advertising revenues have been declining for some content, subscriptions models have been adopted to complement advertising

    Subscription revenue is good news for media, but still very modest – low 10s of billions globally, compared with TV ad revenue which is $70b in US alone. The media industry cannot rely on online subscriptions alone, even if for some media companies this option does bring in the majority of their digital revenue. Media must also remain focused on advertising – but with ad formats and an ad load appropriate to its customer base.

    As the prediction above foresees, we are likely to see a proliferation of new subscription models in the near future. This brings the question of what this may look like for consumers and providers of content/services.

    Subscription of the future – the ‘micro-subscription’

    When thinking of the future of subscriptions it is important to acknowledge that at the heart of the evolution of the model is the customer experience. A focus on the customer, rather than the transaction, product or the enabling technology, is the driving force of subscription models and their application.

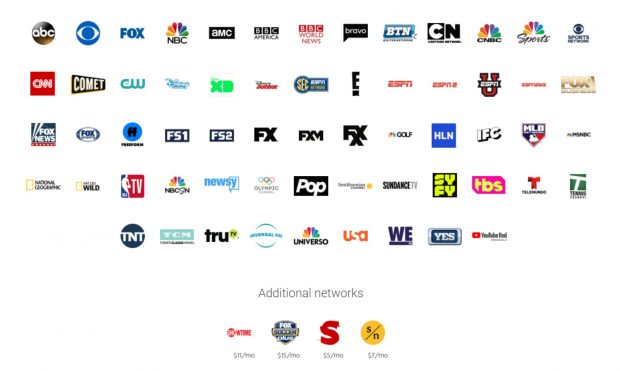
    How will people consume media in the future? What will their viewing/listening experience be like? A scan of services in the market gives us some clues. We are starting to see the growth of OTT content aggregator services which set out to give the customer the most content possible, when they want it. For example, YouTube TV (not yet available in Australia) is an example of possible viewing experience of the future. The service (currently $35/month) aggregates channels (and therefore content), much the same as a cable provider, offering additional subscriptions for niches (e.g. soccer fans). FetchTV in Australia also has a similar aggregation offer allowing it to remain content agnostic.

    Outside of the content offering, the interface for the consumer will also play a role for these services. An aggregator like YouTube TV could neatly tie into the Google Home interface where a user could simply ask ‘Hey Google, show me last night’s NBA game’ and the content would then be beamed to the TV or device. It is unlikely that one service will have all the content available for its basic subscription package, however you can imagine a world where a ‘micro subscription’ would be available for a user to gain access to content not on the platform: ‘I’m sorry, last night’s game is not available, would you like to purchase a subscription for the game and the rest of the game for the month?’. It is possible that we will see these aggregator services cut more deals with content providers or rights holders to enable content to be shown on their platform (for a price). This would lead to a situation when Amazon Prime shows all NFL games on its platform but on YouTube TV you cannot get all games for the basic subscription meaning micro-subscriptions are available for certain games/teams.

    Deloitte’s prediction is highlighting the growth in the number of subscriptions media consumers will have in the future. This aligns to the idea of a proliferation of micro-subscriptions to compliment basic OTT service subscriptions. For this to be true there will also need to be a growth in the ‘share of wallet’ subscription services command – how much a consumer is willing to pay for the content they wish to watch… watch this space!
  • Music streaming: Future business models

    Music streaming: Future business models

    This past week saw RDIO, Spotify’s major rival in streaming music, file for bankruptcy. RDIO was arguably a superior service to Spotify in terms of user experience and music catalog but has failed to capture the market in the way Spotify (20M paying subscribers), Apple Music (6.5M subscribers) and Pandora (81.5M active listeners in 2014) have. The latter has been reported to be acquiring the ‘key assets’ of RDIO for $75M allowing Pandora to build a stronger, ad-supported radio service experience. Pandora’s management believes: “The result will be the industry’s best combination of streaming radio and subscription songs on demand.”

    So…another music streaming service bites the dust. This despite streaming becoming the fastest growing segment of the music industry and the form that most industry leaders and pundits believe is the future of listening. Despite the popularity of the concept (renting, not owning music), it is clear that the business model of streaming is still in its infancy.

    RDIO’s departure could be the first of many for streaming platforms. If this is the case, what is to become of streaming music as a business model? This post explores some of the possibilities for streaming business models and highlights those players best placed to capitalise on growth in streaming service demand.

    Windowing – streaming as a secondary market

    The current and most well known services like Spotify, RDIO (RIP), Apple Music and Google Play take a one-size fits all approach to music. You pay a subscription (~$10/mth) to have the privilege of listening to whatever you want in a catalog of (hundreds of) millions of tracks. One of the problems here is that music is treated like a commodity – all music is the same. For subscribers, there is no discretion regarding to which artist your $10 is paid (the majority may go to artists you don’t listen to) and for artists the rewards are small. The business model of pure streaming as evidenced by RDIO’s bankruptcy and Spotify’s inability to turn a profit is on shaky ground.

    Windowing, a common practice with movies, allows artists to release their new albums to a market that is willing to pay for it directly (>$10) then after a period the music reverts to a streaming service for listeners on subscriptions. Arguably, Apple Music is best placed to capitalise on this model – with iTunes/Apple Music integration. A number of major artists are already beginning to use this strategy – Taylor Swift, Beyonce and this week Adele.

    Enforcing scarcity on infinitely copyable media is a difficult task but not an impossible one. Swift, Adele and the other artists successfully employing a windowing strategy are already big. These artists don’t need to worry about selling out their concerts or reaching new listeners. However, it is a different situation altogether for musicians starting out, and the situation is particularly nuanced for artists in the middle for which windowing may be better. Those looking to get bigger could adopt streaming for free as a primary approach.

    Niche/Exclusive streaming – streaming of niche content for enthusiasts

    The ‘all you can eat’ streaming model has the downside of not being particularly attractive to artists and squeezing the profits of the streaming service and label. Niche services that specialise in a genre (e.g. classic, jazz, hip-hop) or a label (e.g. Blue Note, Columbia) which contain a deeper but smaller catalog of music may emerge as a profitable and viable alternative for many music lovers.

    Equally, video streaming services (e.g. Netflix) offer clues for exclusivity in streaming. Apple has already begun to dabble in ‘exclusive’ content with Dr. Dre’s new album launching exclusively on the service and “Beats radio” and curated stations offering a compelling reason to join or pay a premium in the future.

    Music plus – streaming as a bolt on

    Access to music as part of a subscription to something else has yet to see huge success but there is potential in this model. Amazon Prime is the best example of this but other companies like DropBox, Ebay or Facebook could offer streaming music in this way.

    Amazon Prime affords Amazon customers same-day delivery on all products, e-book rentals, cloud storage on photos etc. Bundling music into this service helps to create stickiness for Prime also offsetting the profitability issues seen by the major streaming services. Currently Prime members get access to 1 million tracks, which would not be considered a serious proposition for music lovers. Whilst this model is potentially more profitable, it is still treating music as a commodity and without the variety and depth of tracks probably best suited to the casual listener.

    Multimedia streaming – cross-media streaming

    Bundling of different content (e.g. music, video, live entertainment) is emerging as a new business model and potentially a very dominant one. As discussed in my last post, Google is uniquely placed to provide a multimedia proposition through YouTube Red. Although currently limited to U.S. users, YouTube Red includes unlimited access to Google Play Music and its supply of 35 million tracks. Google Play plus YouTube Red could make a phenomenal proposition for streaming overall.

    We are at an inflection point for music streaming. Streaming as a concept has won the format battle but the business models that began the new form of music delivery are starting to feel the pressure from subscribers, labels and artists. New business models which balance the demand for music with artists’ needs (e.g. exclusivity, reach) as well as users’ preferences (e.g. niche, ‘all you can eat’, casual) or which smartly package music with other services or media offer new sustainable options for music streaming. The question is which streaming services will win the war.